What makes insuring a home in Los Gatos & Saratoga different?
The short answer: Insuring a home in Los Gatos and Saratoga is different because hillside lots in the Santa Cruz Mountains foothills combine mapped wildfire hazard, earthquake and landslide exposure, and large custom homes with high rebuild costs, so coverage is priced and placed address by address.
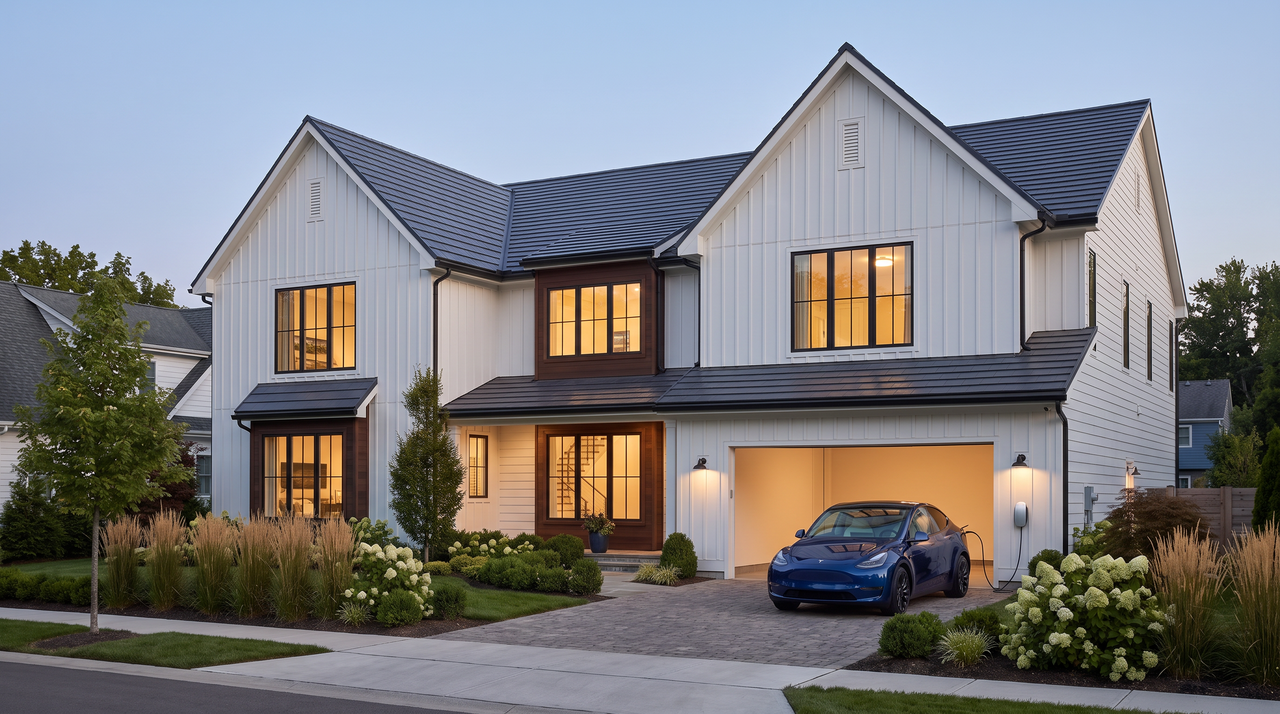
Both towns sit where the valley floor meets the Santa Cruz Mountains. The flats near downtown look like the rest of the valley; the canyons above do not. Insurers rate the exact parcel, so two homes a mile apart can land in very different markets.
Mapped hazard zones
Both towns adopted CAL FIRE's updated fire hazard maps in 2025.
Quake and slope
The 1989 Loma Prieta quake was centered in these mountains, and slopes add landslide exposure.
Big rebuild numbers
The median owner-occupied home value in both towns is $2,000,000 or more, the top of the Census scale.
Source: U.S. Census Bureau QuickFacts, Los Gatos town and Saratoga city, ACS 2020–2024 5-year estimates. Owner-occupied rate: 86.4% in Saratoga, 64.9% in Los Gatos.
For the valley-floor baseline, see our San Jose & Silicon Valley insurance guide. The Campbell & Willow Glen guide covers the flatter neighborhoods just north of Los Gatos.
Are Los Gatos and Saratoga in a high fire hazard zone?
The short answer: Parts of both towns are: the mapped hazard is concentrated in southern Los Gatos's hillsides and Saratoga's western hillsides, so whether a home is in a Fire Hazard Severity Zone depends on the 2025 map for its parcel.
CAL FIRE released updated Local Responsibility Area Fire Hazard Severity Zone maps on February 24, 2025. They rate areas moderate, high, or very high based on fuel, slope, fire weather, and wind, per the Santa Clara County Fire Department.
Los Gatos
The Town adopted the updated map through Ordinance 2374 in June 2025 (Town of Los Gatos). Its 2040 General Plan safety element, adopted in 2022 before the new maps, described more than half of the southern portion of the Town as Very High zone; the 2025 map is the current reference. The Town's 2024 wildfire protection plan describes its wildland-urban interface as primarily Very High zone areas on the southern side of town, with steep, winding, narrow roads that can make evacuation difficult.
Saratoga
The City of Saratoga redrew its wildland-urban interface after the 2025 map changes. That boundary covers the mapped zones plus a small buffer, predominantly on the western hillsides. Every property in it is subject to brush abatement.
Why is home insurance in Los Gatos so expensive, and can I still get coverage?
The short answer: Los Gatos home insurance costs more mainly because of wildfire risk scores and high rebuild costs, but coverage is usually available through a standard carrier, a brokered market, or the FAIR Plan with DIC.
Two numbers drive most hillside premiums: your wildfire risk score and your dwelling limit, which tracks rebuild cost. A large custom home on a brushy slope pushes both up at once.
We haven't found a reliable published premium average for Los Gatos or Saratoga alone. Regional figures, with their sample profiles, are in what home insurance costs in Silicon Valley. Your parcel's score matters more than the ZIP average.
Your wildfire risk score is not a secret
Insurers must give you your property's wildfire risk score, and you have the right to appeal it, per the California Department of Insurance (2022). Ask for the score in writing. If it ignores work you've done, appeal with photos and receipts.
Mitigation credits you can document
The Safer from Wildfires list includes a Class A roof, ember-resistant vents, a 5-foot ember-resistant zone, clearing under decks, moving sheds 30 feet away, defensible space, and community programs such as Firewise USA. The department says every listed action qualifies for a discount; our Safer from Wildfires discount guide covers the paperwork. Also check for a separate wildfire deductible on your policy.
What should I do if I'm non-renewed in the Los Gatos or Saratoga hills?
The short answer: If you're non-renewed in the Los Gatos or Saratoga hills, use the 75-day notice window to confirm the reason, check for a wildfire moratorium, document your mitigation, and line up replacement coverage before the policy ends.
A non-renewal letter comes with a clock and with rights. Insurance Code section 678 requires the notice at least 75 days before expiration, with the specific reason and a statement that the Department of Insurance can review it (statute text).
- Read the stated reason
Wildfire exposure, roof condition, brush, or a claim? Some reasons can be fixed. Ask for the risk score behind the decision.
- Check for a moratorium
Under SB 824 (Insurance Code 675.1), after a declared wildfire emergency, insurers can't non-renew a home in a ZIP code within or next to the fire perimeter for one year based solely on its being in a wildfire area, with limited exceptions. The Department of Insurance has a ZIP lookup.
- Document your mitigation
Photos of the roof, vents, and defensible space help with the next market and with a score appeal.
- Call us early
We match hillside homes to the right market: a standard carrier where one fits, select brokered markets where one doesn't, and FAIR Plan plus DIC as the backstop.
The full sequence is in our California non-renewal playbook. Don't let coverage lapse while you shop; lenders typically require continuous hazard coverage.
How does the FAIR Plan work for a hillside home in Los Gatos or Saratoga?
The short answer: The FAIR Plan gives a hillside Los Gatos or Saratoga home basic fire coverage when standard carriers decline, but it covers only named perils, so most owners add a DIC policy.
The FAIR Plan dwelling policy is named-peril: fire and lightning, internal explosion, and smoke, with optional add-ons such as vandalism (California FAIR Plan). It leaves out liability, theft, and water damage, which the Department of Insurance notes takes a companion policy. A difference in conditions (DIC) policy from another market fills most of those gaps.
Source: KRCR, FAIR Plan rate increase report and InsuranceNewsNet (May 2026). Figure as reported in news coverage of a FAIR Plan statement. The FAIR Plan says changes vary by wildfire risk, and some policyholders may see a decrease.
The limit question for large homes
The FAIR Plan's combined homeowners dwelling limit is at least $3 million, raised from $1.5 million (Department of Insurance, 2021). Some custom homes here need a higher rebuild limit, so how the stack is built matters.
We cover the pairing in FAIR Plan + DIC coverage, explained, and the exit path in how to get off the FAIR Plan.
Do I need earthquake and landslide coverage in Los Gatos and Saratoga?
The short answer: Earthquake coverage deserves a real decision in Los Gatos and Saratoga because home policies exclude it and Loma Prieta was centered nearby; landslide is generally excluded altogether.
The magnitude 6.9 Loma Prieta earthquake struck on October 17, 1989, with its epicenter near Loma Prieta peak in the Santa Cruz Mountains on the San Andreas fault system (USGS). USGS notes that the potential for another damaging earthquake in the Santa Cruz Mountains may still exist.
The Los Gatos 2040 General Plan says the town is near the San Andreas, Hayward, and Calaveras faults, that past earthquakes have caused significant damage in the Town through ground shaking and landslides, and that landslides are a risk in most of the southern and eastern portions of the Town.
Earthquake: a separate policy
Standard home policies exclude earthquake. CEA deductibles run 5% to 25% of the dwelling limit, and homes with more than $1 million of dwelling coverage are limited to 15%, 20%, or 25% (CEA). Our CEA vs. private earthquake guide compares the options.
Landslide and debris flow: mostly excluded
The Department of Insurance says home policies generally exclude mudflow, debris flow, landslide, and earth movement, though ensuing fire is typically covered. If a wildfire was the efficient proximate cause of a later mudflow, there may be coverage, so file the claim. NFIP flood insurance covers some mudflow, but not landslides.
How should a large custom home in Los Gatos or Saratoga be insured?
The short answer: A large custom home in Los Gatos or Saratoga should be insured to its full rebuild cost with extended replacement cost added, and paired with umbrella liability coverage sized to the household's assets.
Market value isn't the target; the land survives a fire. On a hillside custom home, though, rebuild cost runs high. Slope, retaining walls, equipment access, custom finishes, and code upgrades all add to it.
- Rebuild-cost dwelling limit. Get a fresh estimate reflecting square footage, finish level, and site. The method is in how much dwelling coverage you need in Silicon Valley.
- Extended replacement cost. A cushion above the limit, commonly 25% to 50%, for post-disaster demand surge.
- Replacement cost on contents. See replacement cost vs. actual cash value.
- Other structures. Guest houses and long retaining walls may need more than the default percentage.
Umbrella liability
Significant equity means more to lose in a lawsuit. An umbrella sits above home and auto liability, typically starting at $1 million. Pools, household staff, and teen drivers are common reasons to add one; see how much umbrella insurance you need. Our Silicon Valley home insurance page shows how we build hillside policies.
What should Highway 17 and Highway 85 commuters know about auto insurance?
The short answer: Highway 17 and Highway 85 commuters are priced mainly on driving record, mileage, and experience under Prop 103, so focus on liability above 30/60/15 and uninsured motorist coverage.
The Governors Highway Safety Association has described Highway 17 between Los Gatos and Santa Cruz as notorious for narrow lanes, a lack of shoulders, and sharp curves; a CHP-led "Safe on 17" task force formed in 1999 to address its collision rates (GHSA, 2012).
Under Prop 103, California auto rates rest mainly on driving record, annual mileage, and years of experience. Credit scores aren't used, and qualifying good drivers get a 20% discount. Report commute miles accurately.
- Liability above the minimum. The 30/60/15 minimum (since January 1, 2025) is a legal floor, not a fit for a household with a $2 million home. See the 30/60/15 minimum explained.
- Uninsured motorist coverage. The Insurance Research Council estimated 20.4% of California drivers were uninsured in 2023 (Insurance Information Institute). Our uninsured motorist guide explains it.
- Bundling. Placing auto insurance with your home policy typically earns a multi-policy discount.
The bottom line
Insuring a home in Los Gatos or Saratoga comes down to your exact parcel. Find your zone on the 2025 maps. Get your wildfire risk score and appeal it if it's outdated. Insure the rebuild, not the market price, with extended replacement cost on top. Decide on earthquake deliberately, and know landslide is largely outside the policy.
Non-renewed? The 75-day notice window gives you time when you start early. We work with more than one market, so one carrier's no isn't the end of the search. Call (408) 669-4068 or start a quote.
Los Gatos & Saratoga insurance FAQ
Is all of Los Gatos in a very high fire hazard severity zone?
No. The hazard is concentrated in the hills. The Town's 2040 General Plan safety element, adopted in 2022, described more than half of the southern portion of Los Gatos as Very High Fire Hazard Severity Zone. The Town adopted CAL FIRE's updated map in June 2025, and that map is the current reference. Because the 2022 description predates it, check the adopted map for your parcel.
How do I find out if my Saratoga home is in a fire hazard zone?
Start with the City of Saratoga's fire prevention page, which links its wildland-urban interface map. The city redrew that boundary after CAL FIRE's 2025 map changes, and it covers mainly the western hillsides. If your home is inside it, expect brush abatement rules and close insurer attention to roof type and defensible space.
Does homeowners insurance cover a landslide in the Santa Cruz Mountains?
Generally no. The California Department of Insurance says home policies generally exclude landslide, mudflow, debris flow, and earth movement, though ensuing fire is typically covered. If a wildfire caused a later mudflow, there may be coverage, so file the claim. NFIP flood insurance covers some flood-caused mudflow but excludes landslides entirely.
Is the FAIR Plan enough for a large custom home in Saratoga?
Usually not by itself. The FAIR Plan covers named perils like fire, lightning, internal explosion, and smoke, with a combined homeowners dwelling limit of at least $3 million. It leaves out liability, theft, and water damage, so most owners add a DIC policy. A home that needs a higher rebuild limit needs a carefully built stack.
Should I buy earthquake insurance for a Los Gatos home?
It deserves a deliberate decision. Home policies exclude earthquake, and the 1989 Loma Prieta quake was centered in the Santa Cruz Mountains. CEA deductibles run 5% to 25% of the dwelling limit, and homes with more than $1 million of dwelling coverage are limited to 15% to 25%. Compare that deductible with your savings.
Do Highway 17 commuters pay more for car insurance?
Not because of the road name. Under Prop 103, California auto rates rest mainly on driving record, annual miles, and years of experience, so a long commute matters through mileage. A clean record keeps the 20% good driver discount. We recommend liability well above 30/60/15 and uninsured motorist coverage for mountain commuters.